An annuity-due is an annuity whose payments are made at the beginning of each period. Deposits in savings, rent or lease payments, and insurance premiums are examples of annuities due.
| ↓ | ↓ | ... | ↓ | payments | |
| ——— | ——— | ——— | ——— | — | |
| 0 | 1 | ... | n-1 | n | periods |
Because each annuity payment is allowed to compound for one extra period. Thus, the present and future values of an annuity-due can be calculated through the formula:

and
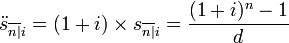
where are the number of terms, is the per term interest rate, and is the effective rate of discount given by .
Future and present values for annuities due are related as:

and

Example: The final value of a 7 year annuity-due with annual interest rate 9% and monthly payments of $100:

Note that in Excel, the PV and FV functions take on optional fifth argument which selects from annuity-immediate or annuity-due.
An annuity-due with n payments is the sum of one annuity payment now and an ordinary annuity with one payment less, and also equal, with a time shift, to an ordinary annuity with one payment more, minus the last payment. Thus we have:
- (value at the time of the first of n payments of 1)
- (value one period after the time of the last of n payments of 1)
Read more about this topic: Annuity (finance Theory)